Income Tax
Clause 22 – Form 3CD
Important reporting requirements relating to payments to Micro and Small Enterprises under the MSMED Act, 2006 and disallowance under Section 43B(h).
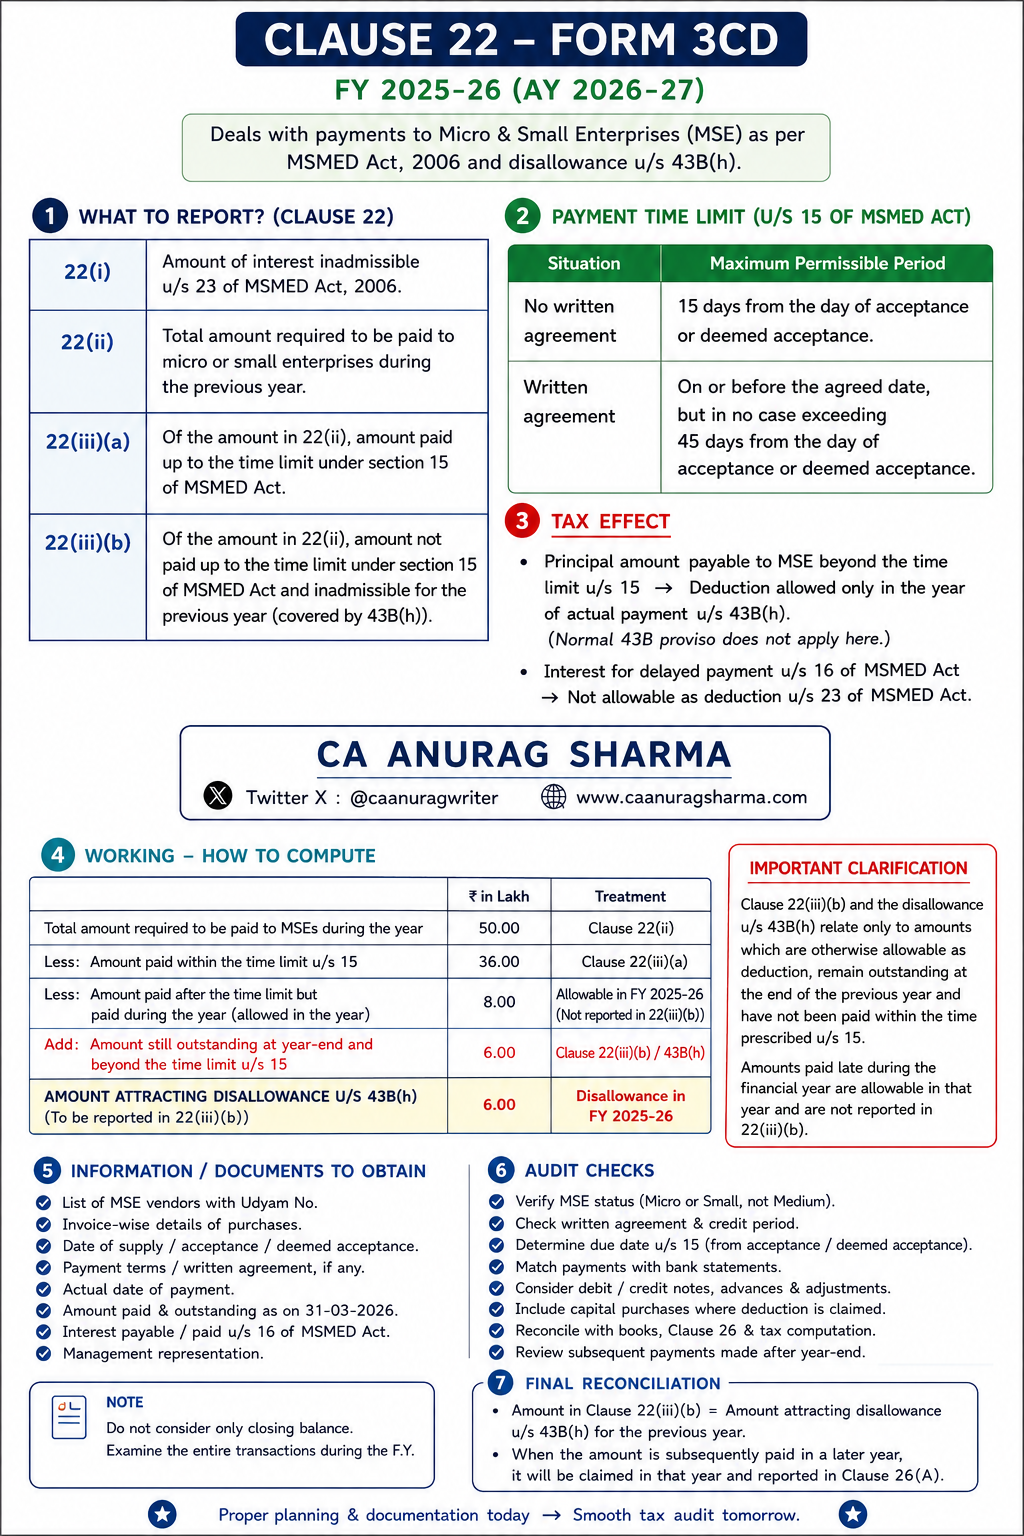
Clause 22 – Form 3CD
Clause 22 of Form 3CD deals with payments to Micro and Small Enterprises covered under the MSMED Act, 2006 and the related tax implications under Section 43B(h) of the Income-tax Act.
What is reported under Clause 22?
Clause 22 requires reporting of certain amounts relating to Micro and Small Enterprises and the payments made to them during the financial year.
- Amount of interest inadmissible under the MSMED Act.
- Total amount required to be paid to Micro and Small Enterprises during the previous year.
- Amount paid within the time limit prescribed under Section 15 of the MSMED Act.
- Amount not paid within the prescribed time limit and subject to disallowance under Section 43B(h).
Payment Time Limit
Where there is no written agreement, payment is generally required within 15 days from the date of acceptance or deemed acceptance.
Where a written agreement exists, payment must be made within the agreed period, subject to the statutory maximum period of 45 days.
Tax Effect under Section 43B(h)
Amounts payable to Micro and Small Enterprises beyond the prescribed payment period may attract disallowance under Section 43B(h).
The deduction is generally allowed in the year in which the payment is actually made, subject to the applicable provisions of the Income-tax Act.
Important
Taxpayers and tax professionals should examine the underlying transactions, acceptance dates, agreed payment terms and actual payment dates rather than relying only on the closing outstanding balance.
Proper reconciliation between the books of account, vendor records and tax computation is important while preparing Form 3CD.